- Article
- Global Investment Research
- Data science
HSBC Funding the Future Survey - AI and the IPO window
The tenth edition of our proprietary Funding the Future Survey finds that private market investors see stronger deal prices, but raising fresh funds remains tough. Their concerns about AI are also changing.
Carried out by Survation, this survey captures the views of 217 global investors representing a significant portion of the private and public high-growth investment community. Survey participants represented AUM of USD3.6trn, of which cUSD1.5trn is attributed to VC and private equity (PE) investors. The fieldwork took place from 15 September to 12 October 2026.
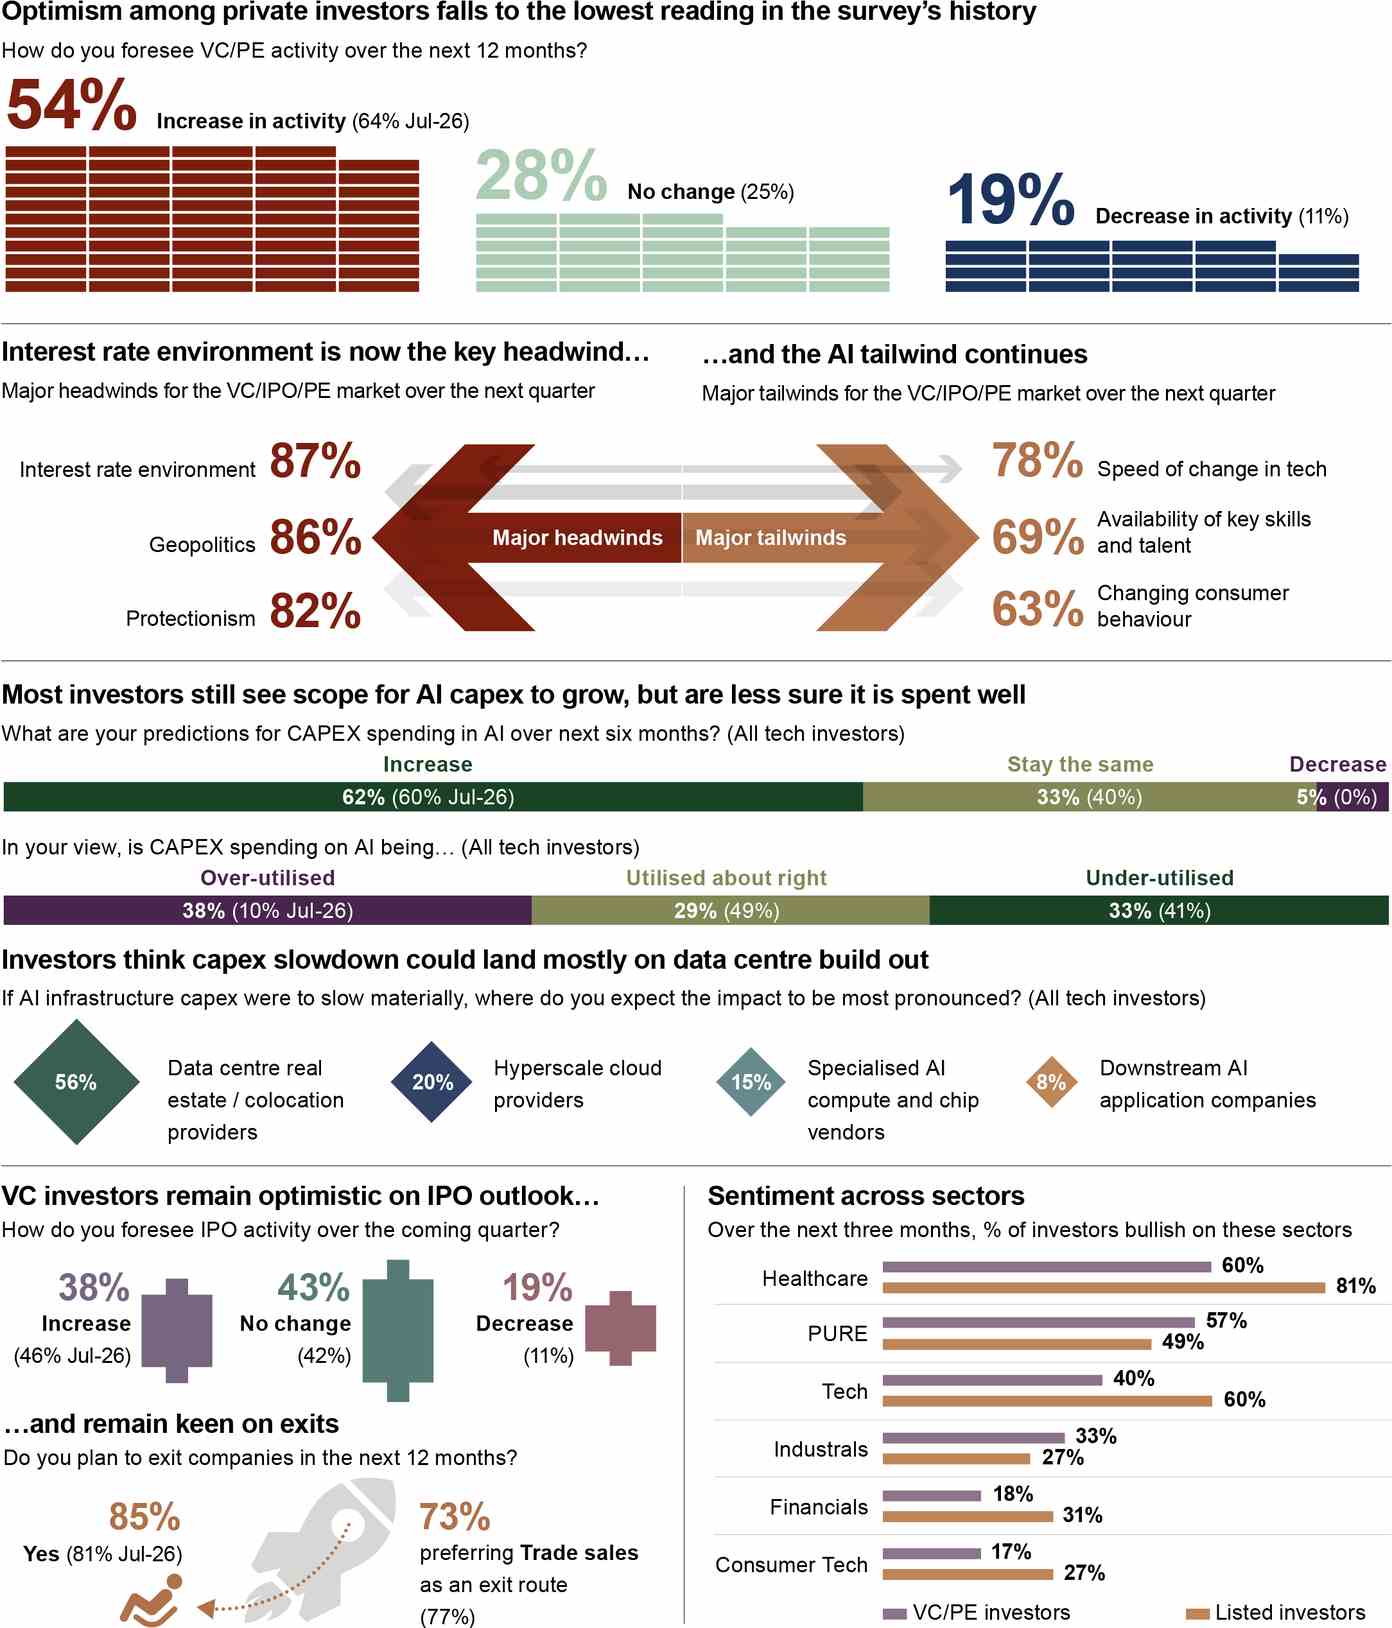
Private investors are modestly more confident about the coming quarter than they were in July, with 48% expecting an increase in VC and PE activity, against 44%. The 12-month view has softened to 54% from 64%, though as the regional section shows, that fall is concentrated in Asia Pacific rather than spread across the market.
54%
Of private investors are confident about the coming 12 months, the lowest in the survey’s history
The deals in front of investors look better than at any point in the survey's history. Some 51% report that recent financings in their universe have mostly been up rounds, the highest reading we have recorded, while only 3% report mostly down rounds, the lowest. On aggregate it would seem the repricing that defined 2022 and 2023 appears to have worked its way through. On closer inspection, however, AI deals are a big driver of this trend.
What has not recovered is the supply of new capital. Only 21% of private investors expect fundraising conditions to improve over the coming year, down from 34% in July, and the deterioration holds in every region we track. The share reporting that their dry powder has increased over the last twelve months has fallen to 23%, a series low. Investors are deploying faster than they are raising.
75%
Of private investors expect a US interest rate hike
The macro backdrop has moved against them. Three quarters of private investors and 77% of listed investors now expect the next move in US interest rates to be a hike, having expected no change as recently as July. Market pricing has moved the same way in the past few months, so the survey is confirming the repricing. For private markets the consequences of the changing rate environment have become the single largest headwind investors name, cited by 87% against 66% in July, and expectations around ask/bid spreads have deteriorated almost as sharply.
AI remains the overwhelming answer to where private capital is going, named by 85% of private investors as the sector they expect to attract the most private-market investment over the coming quarter.
Some 56% now think a meaningful slowdown in AI infrastructure spending is likely within six to twelve months, up from 51%, with those calling it very likely rising to 20% from 11%. Asked where such a slowdown would be felt most, 55% now name data centre real estate and colocation providers, against 24% in July. Hyperscale cloud providers have fallen from 33% to 20%, and specialised AI compute and chip vendors from 25% to 15%. Four further survey responses point the same way: energy and power availability has risen to the second-largest potential upside for AI capex; anxiety about chip supply has eased; infrastructure and energy has overtaken technology as the expected growth area in private direct lending; and the energy transition has become the fastest-rising of the long-term themes we track.
Against all this, we think investors remain committed to the theme but are more willing to act on disappointment than they were earlier in the year. Some 29% would now cut AI exposure by a quarter if their named downside materialised, against 7% in July.
85%
Of private investors are planning to exit at least one portfolio company in the next twelve months
Exit intent is at a series high, with 85% of private investors planning to exit at least one portfolio company in the next twelve months. Trade sales remain the preferred route at 73%, but buyouts have fallen to 35% from 46%, consistent with a higher expected cost of leverage, while IPOs (initial public offerings) have risen to 35% and mergers to 31% from 17%.
What investors expect to list has shifted decisively towards AI, named by 63% against 36% in July. One long-standing finding from our survey has changed in this wave: the share of investors preferring their portfolio companies to list in the US has fallen to 57% from 79%, while the share stating a preference for an Asian listing has doubled to 18%, similar to those preferring EMEA (18%).
The following analyst(s), who is(are) primarily responsible for this document, certifies(y) that the opinion(s), views or forecasts expressed herein accurately reflect their personal view(s) and that no part of their compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report: Shiva Joon, CFA
This document has been issued by the Research Department of HSBC.
HSBC and its affiliates will from time to time sell to and buy from customers the securities/instruments, both equity and debt (including derivatives) of companies covered in HSBC Research on a principal or agency basis or act as a market maker or liquidity provider in the securities/instruments mentioned in this report.
Analysts, economists, and strategists are paid in part by reference to the profitability of HSBC which includes investment banking, sales & trading, and principal trading revenues.
Whether, or in what time frame, an update of this analysis will be published is not determined in advance.
For disclosures in respect of any company mentioned in this report, please see the most recently published report on that company available at www.hsbcnet.com/research.
HSBC may use Artificial Intelligence (AI) tools approved for adoption within HSBC in the development of its research reports, utilizing these technologies to analyse large volumes of data, enhance efficiency and improve the overall user experience. This includes but is not limited to paraphrasing, developing suitable captions and supporting data visualisation. It is important to note that while AI tools assist in various aspects of report creation, all investment recommendations and opinions presented herein are formulated and approved exclusively by our research analysts. The final content of the report reflects the professional judgement and expertise of our research analysts, ensuring compliance with regulatory standards and maintaining the integrity of our research process.
Additional disclosures
- This report is dated as at 21 October 2026.
- All market data included in this report are dated as at close 19 October 2026, unless a different date and/or a specific time of day is indicated in the report.
- HSBC has procedures in place to identify and manage any potential conflicts of interest that arise in connection with its Research business. HSBC's analysts and its other staff who are involved in the preparation and dissemination of Research operate and have a management reporting line independent of HSBC's Investment Banking business. Information Barrier procedures are in place between the Investment Banking, Principal Trading, and Research businesses to ensure that any confidential and/or price sensitive information is handled in an appropriate manner.
- You are not permitted to use, for reference, any data in this document for the purpose of (i) determining the interest payable, or other sums due, under loan agreements or under other financial contracts or instruments, (ii) determining the price at which a financial instrument may be bought or sold or traded or redeemed, or the value of a financial instrument, and/or (iii) measuring the performance of a financial instrument or of an investment fund.
This document has been issued by HSBC Bank plc, which has based this document on information obtained from sources it believes to be reliable but which it has not independently verified. Neither HSBC Bank plc nor any member of its group companies (“HSBC”) make any guarantee, representation or warranty nor accept any responsibility or liability as to the accuracy or completeness of this document and is not responsible for errors of transmission of factual or analytical data, nor is HSBC liable for damages arising out of any person’s reliance on this information. The information and opinions contained within the report are based upon publicly available information at the time of publication, represent the present judgment of HSBC and are subject to change without notice.
This document is not and should not be construed as an offer to sell or solicitation of an offer to purchase or subscribe for any investment or other investment products mentioned in it and/or to participate in any trading strategy. It does not constitute a prospectus or other offering document. Information in this document is general and should not be construed as personal advice, given it has been prepared without taking account of the objectives, financial situation or needs of any particular investor. Accordingly, investors should, before acting on it, consider the appropriateness of the information, having regard to their objectives, financial situation and needs. If necessary, seek professional investment and tax advice.
The decision and responsibility on whether or not to purchase, subscribe or sell (as applicable) must be taken by the investor. In no event will any member of the HSBC group be liable to the recipient for any direct or indirect or any other damages of any kind arising from or in connection with reliance on any information and materials herein.
Past performance is not necessarily a guide to future performance. The value of any investment or income may go down as well as up and you may not get back the full amount invested. Where an investment is denominated in a currency other than the local currency of the recipient of the research report, changes in the exchange rates may have an adverse effect on the value, price or income of that investment. In case of investments for which there is no recognised market it may be difficult for investors to sell their investments or to obtain reliable information about its value or the extent of the risk to which it is exposed. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors.
This document is for information purposes only and may not be redistributed or passed on, directly or indirectly, to any other person, in whole or in part, for any purpose. The distribution of this document in other jurisdictions may be restricted by law, and persons into whose possession this document comes should inform themselves about, and observe, any such restrictions. By accepting this report, you agree to be bound by the foregoing instructions. If this report is received by a customer of an affiliate of HSBC, its provision to the recipient is subject to the terms of business in place between the recipient and such affiliate. The document is intended to be distributed in its entirety. Unless governing law permits otherwise, you must contact a HSBC Group member in your home jurisdiction if you wish to use HSBC Group services in effecting a transaction in any investment mentioned in this document.
Certain investment products mentioned in this document may not be eligible for sale in some states or countries, and they may not be suitable for all types of investors. Investors should consult with their HSBC representative regarding the suitability of the investment products mentioned in this document.
HSBC and/or its officers, directors and employees may have positions in any securities in companies mentioned in this document. HSBC may act as market maker or may have assumed an underwriting commitment in the securities of companies discussed in this document (or in related investments), may sell or buy securities and may also perform or seek to perform investment banking or underwriting services for or relating to those companies and may also be represented on the supervisory board or any other committee of those companies.
From time to time research analysts conduct site visits of covered issuers. HSBC policies prohibit research analysts from accepting payment or reimbursement for travel expenses from the issuer for such visits.
HSBC Bank plc is registered in England No 14259, is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority and is a member of the London Stock Exchange.
Should you wish to use AI technology (computational, statistical, machine-learning or other artificial intelligence techniques to infer or learn from data to find patterns, take actions, make decisions, or generate output) to help you analyse, summarise or evaluate this publication and/or any other research materials provided to you by HSBC, you shall seek HSBC consent in advance of any such use and not upload this publication and/or any other research materials produced by HSBC to an AI system or otherwise use AI technology in connection with the research services HSBC provides to you without our consent.
© Copyright 2026, HSBC Bank plc, ALL RIGHTS RESERVED. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the issuer of the report.
HSBC Emerging Markets Sentiment Survey - Less bull, more bite
This edition – the 25th in the series – captures a shift in investors’ approach to emerging markets (EM). Bullish expectations have moderated, but risk appetite has recovered. Investors also have more cash available to put to work.