- Article

- Global Investment Research
- Emerging markets
- General Research Insights
HSBC Emerging Markets Sentiment Survey - Less bull, more bite
Our latest Emerging Markets Sentiment Survey finds the bulls still in the majority, and a few bears joining the celebrations.
Bulls with dry powder
This edition – the 25th in the series – captures a shift in investors’ approach to emerging markets (EM). Bullish expectations have moderated, but risk appetite has recovered. Investors also have more cash available to put to work. The appetite for EM is intact, even as the conviction about the short-term outlook has softened.
Conducted by Survation between 3 August and 16 September 2026, the survey covers 102 investors from 102 institutions, representing USD424bn of EM assets under management. The share of bullish respondents declined to 50%, from 60% in June, while neutral views increased to 44%, from 31%. Notably, bears reappeared at 5% after being entirely absent for three consecutive surveys, bringing net sentiment down to 45%.
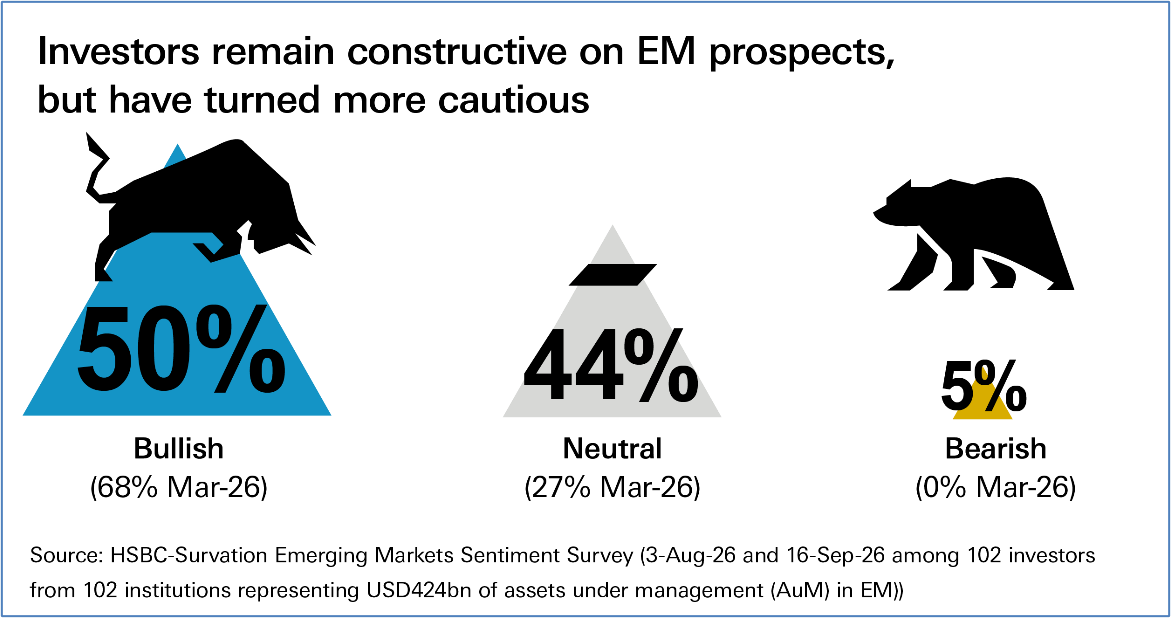
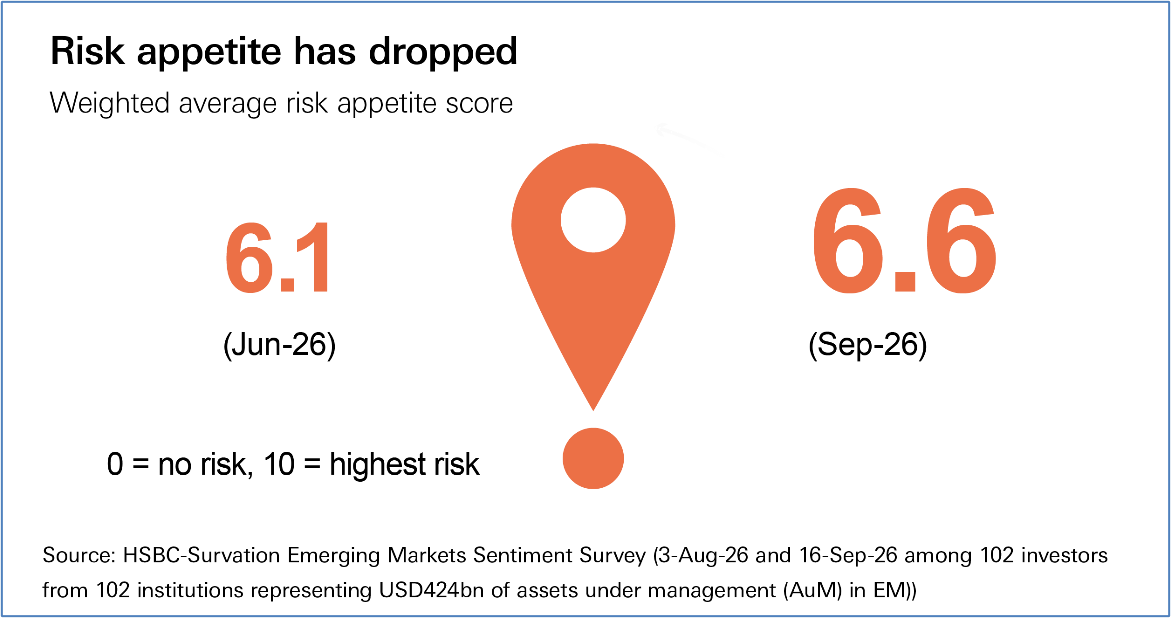
Nevertheless, this marks the 16th consecutive survey with a positive net reading. Softer sentiment has coincided with a greater willingness to take risk, with the weighted average risk appetite score (on a scale where 0 is no risk, and 10 the highest risk) rising to 6.6, from 6.1.
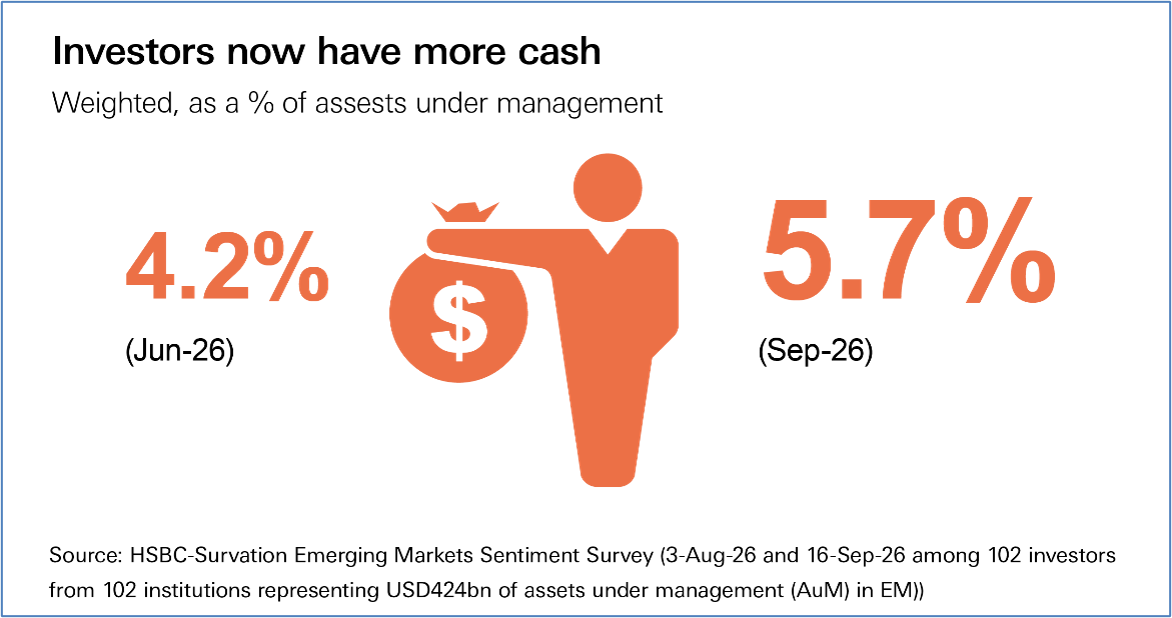
Investors have also replenished their reserves. Weighted average cash holdings increased to 5.7% of assets under management, from 4.2%, the highest level since December 2023. Meanwhile, 40% of investors plan to reduce their cash holdings over the next three months, up from 18%, while only 11% intend to increase them. This combination of stronger risk appetite and greater dry powder could support EM if the right catalysts emerge.
The macro backdrop looks more supportive, although inflation concerns remain elevated. Net expectations for EM growth acceleration recovered to 45%, from 26%, largely reflecting a sharp decline in the proportion of investors anticipating a slowdown. Meanwhile, the proportion of investors expecting higher rather than lower EM inflation declined to 55%, from 80%.
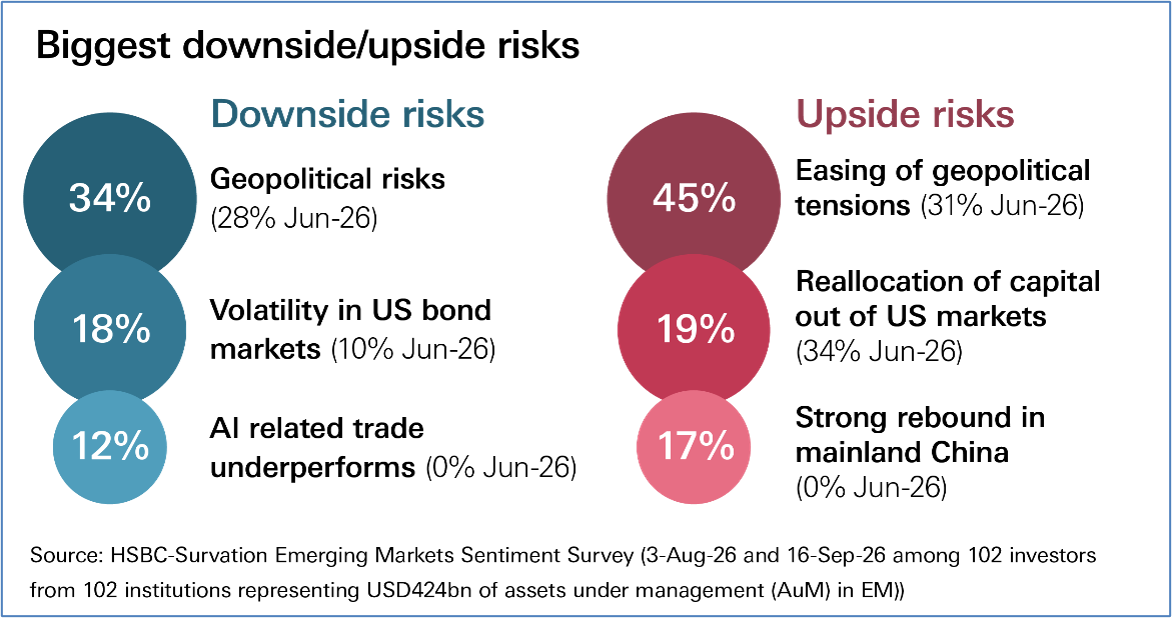
Geopolitics will be central to whether investors deploy their cash. It is now the leading downside risk, cited by 34%, while an easing of tensions is the largest upside catalyst, selected by 45%. US bond market volatility ranks second among downside risks, while capital reallocation out of the US remains the second-largest upside catalyst. A rebound in mainland China and outperformance of the AI trade also feature among potential supports.
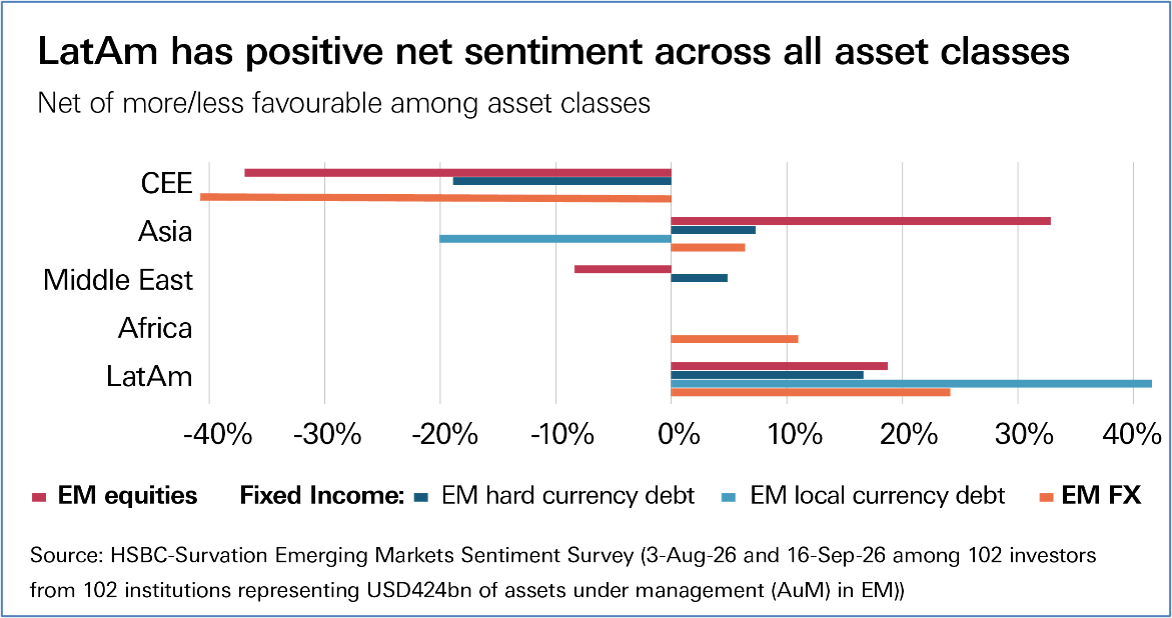
On strategy, Latin America stands out the only region with positive net sentiment across all asset classes. Asia remains the preferred equity region, but enthusiasm has moderated. Investors are still constructive on EM equities, with 56% expecting further gains. In other asset classes, EM FX sentiment picked up on a net basis; and within fixed income, there is a marginal preference for local currency debt.
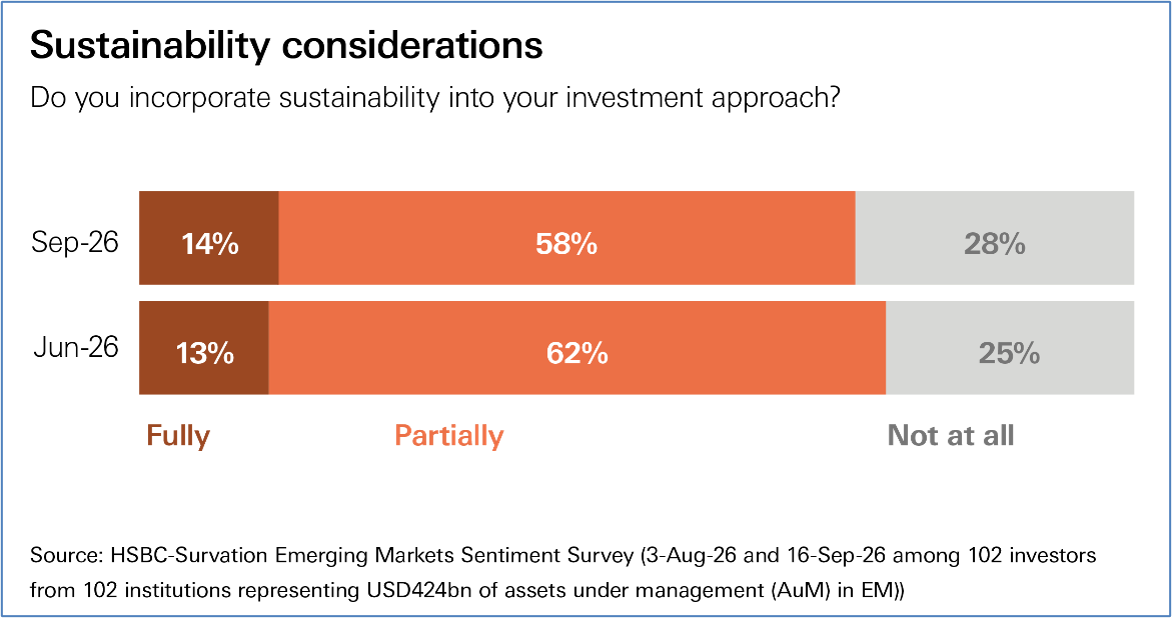
On sustainability, integration into investment decision-making continues to increase. However, investors still identify insufficient funding and a lack of regulation as the main obstacles to achieving net zero, highlighting the need for stronger government support.
Would you like to find out more? Subscribers to HSBC Global Investment Research can click here* to read the full report.
To learn more about HSBC Global Investment Research, including how to subscribe, please email us at AskResearch@HSBC.com
*Please note that by clicking on this link you are leaving the HSBC Corporate & Institutional Banking website, therefore please be aware that the external site policies will differ from our website terms and conditions and privacy policy. The next site will open in a new browser window or tab
The following analyst(s), who is(are) primarily responsible for this document, certifies(y) that the opinion(s), views or forecasts expressed herein accurately reflect their personal view(s) and that no part of their compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report: Ali Cakiroglu
This document has been issued by the Research Department of HSBC.
HSBC and its affiliates will from time to time sell to and buy from customers the securities/instruments, both equity and debt (including derivatives) of companies covered in HSBC Research on a principal or agency basis or act as a market maker or liquidity provider in the securities/instruments mentioned in this report.
Analysts, economists, and strategists are paid in part by reference to the profitability of HSBC which includes investment banking, sales & trading, and principal trading revenues.
Whether, or in what time frame, an update of this analysis will be published is not determined in advance.
For disclosures in respect of any company mentioned in this report, please see the most recently published report on that company available at www.hsbcnet.com/research.
HSBC may use Artificial Intelligence (AI) tools approved for adoption within HSBC in the development of its research reports, utilizing these technologies to analyse large volumes of data, enhance efficiency and improve the overall user experience. This includes but is not limited to paraphrasing, developing suitable captions and supporting data visualisation. It is important to note that while AI tools assist in various aspects of report creation, all investment recommendations and opinions presented herein are formulated and approved exclusively by our research analysts. The final content of the report reflects the professional judgement and expertise of our research analysts, ensuring compliance with regulatory standards and maintaining the integrity of our research process.
Additional disclosures
- This report is dated as at 22 September 2026.
- All market data included in this report are dated as at close 18 September 2026, unless a different date and/or a specific time of day is indicated in the report.
- HSBC has procedures in place to identify and manage any potential conflicts of interest that arise in connection with its Research business. HSBC's analysts and its other staff who are involved in the preparation and dissemination of Research operate and have a management reporting line independent of HSBC's Investment Banking business. Information Barrier procedures are in place between the Investment Banking, Principal Trading, and Research businesses to ensure that any confidential and/or price sensitive information is handled in an appropriate manner.
- You are not permitted to use, for reference, any data in this document for the purpose of (i) determining the interest payable, or other sums due, under loan agreements or under other financial contracts or instruments, (ii) determining the price at which a financial instrument may be bought or sold or traded or redeemed, or the value of a financial instrument, and/or (iii) measuring the performance of a financial instrument or of an investment fund.
This document has been issued by HSBC Bank plc, which has based this document on information obtained from sources it believes to be reliable but which it has not independently verified. Neither HSBC Bank plc nor any member of its group companies (“HSBC”) make any guarantee, representation or warranty nor accept any responsibility or liability as to the accuracy or completeness of this document and is not responsible for errors of transmission of factual or analytical data, nor is HSBC liable for damages arising out of any person’s reliance on this information. The information and opinions contained within the report are based upon publicly available information at the time of publication, represent the present judgment of HSBC and are subject to change without notice.
This document is not and should not be construed as an offer to sell or solicitation of an offer to purchase or subscribe for any investment or other investment products mentioned in it and/or to participate in any trading strategy. It does not constitute a prospectus or other offering document. Information in this document is general and should not be construed as personal advice, given it has been prepared without taking account of the objectives, financial situation or needs of any particular investor. Accordingly, investors should, before acting on it, consider the appropriateness of the information, having regard to their objectives, financial situation and needs. If necessary, seek professional investment and tax advice.
The decision and responsibility on whether or not to purchase, subscribe or sell (as applicable) must be taken by the investor. In no event will any member of the HSBC group be liable to the recipient for any direct or indirect or any other damages of any kind arising from or in connection with reliance on any information and materials herein.
Past performance is not necessarily a guide to future performance. The value of any investment or income may go down as well as up and you may not get back the full amount invested. Where an investment is denominated in a currency other than the local currency of the recipient of the research report, changes in the exchange rates may have an adverse effect on the value, price or income of that investment. In case of investments for which there is no recognised market it may be difficult for investors to sell their investments or to obtain reliable information about its value or the extent of the risk to which it is exposed. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors.
This document is for information purposes only and may not be redistributed or passed on, directly or indirectly, to any other person, in whole or in part, for any purpose. The distribution of this document in other jurisdictions may be restricted by law, and persons into whose possession this document comes should inform themselves about, and observe, any such restrictions. By accepting this report, you agree to be bound by the foregoing instructions. If this report is received by a customer of an affiliate of HSBC, its provision to the recipient is subject to the terms of business in place between the recipient and such affiliate. The document is intended to be distributed in its entirety. Unless governing law permits otherwise, you must contact a HSBC Group member in your home jurisdiction if you wish to use HSBC Group services in effecting a transaction in any investment mentioned in this document.
Certain investment products mentioned in this document may not be eligible for sale in some states or countries, and they may not be suitable for all types of investors. Investors should consult with their HSBC representative regarding the suitability of the investment products mentioned in this document.
HSBC and/or its officers, directors and employees may have positions in any securities in companies mentioned in this document. HSBC may act as market maker or may have assumed an underwriting commitment in the securities of companies discussed in this document (or in related investments), may sell or buy securities and may also perform or seek to perform investment banking or underwriting services for or relating to those companies and may also be represented on the supervisory board or any other committee of those companies.
From time to time research analysts conduct site visits of covered issuers. HSBC policies prohibit research analysts from accepting payment or reimbursement for travel expenses from the issuer for such visits.
HSBC Bank plc is registered in England No 14259, is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority and is a member of the London Stock Exchange.
© Copyright 2026, HSBC Bank plc, ALL RIGHTS RESERVED. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the issuer of the report.
Issuer of report
HSBC Bank plc
HSBC Emerging Markets Sentiment Survey – No country for bears
The previous edition of the survey found that the Middle East conflict and the associated surge in commodity prices – oil and gas in particular – added a fresh layer of uncertainty.